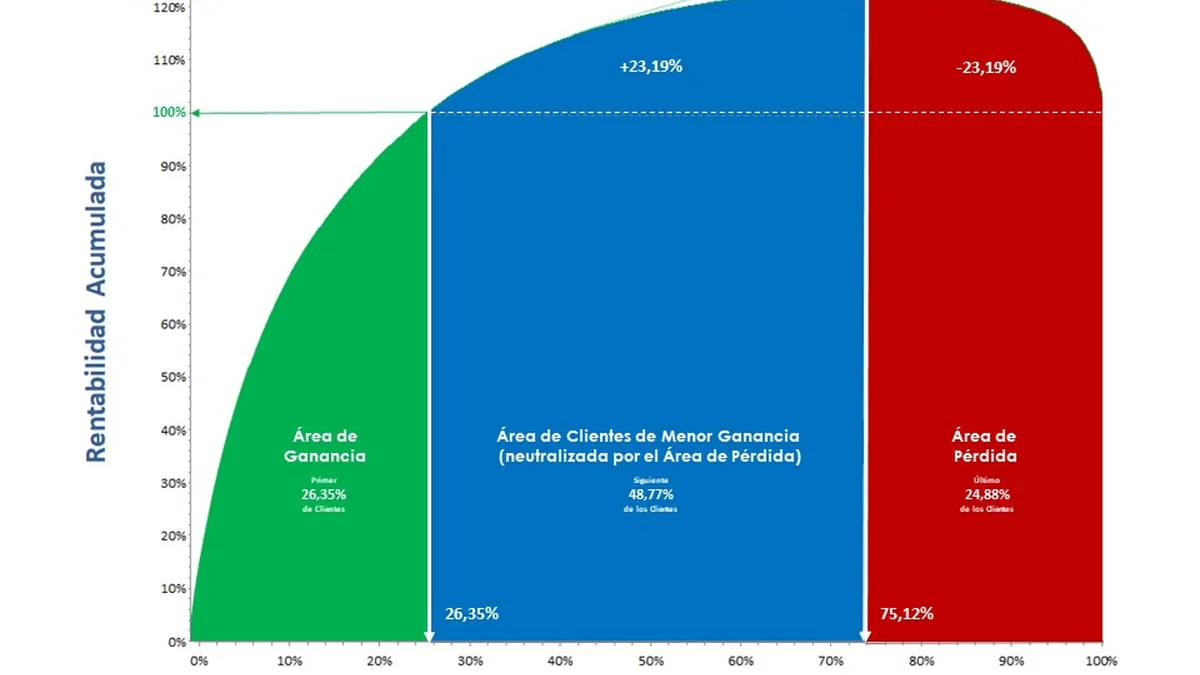
Profitability
| Country of origin | United States |
|---|---|
| First created | 1970s |
| Original use | Business planning and financial modeling |
| Key metric | Net profit margin |
| Time to achieve | Varies by industry and business model |
| Primary drivers | Revenue growth and cost management |
| Common framework | Break-even analysis |
| Stage context | Pre-launch to early growth |
Origin and history
The concept of Profitability as a distinct and critical stage for a business founder originates from modern Western business management theory, particularly in the late 20th century. It evolved from earlier industrial-era models that focused simply on profit maximization for established corporations. The formalization of "the founder stage" as a framework, which includes Profitability as a pivotal decision point, gained prominence with the rise of venture capital and startup ecosystems in the 1990s and 2000s. This period saw the articulation of distinct growth phases, moving from ideation to scaling, with Profitability marking a key transition. The framework was developed to provide structure to the otherwise chaotic journey of new venture creation, offering founders a lens through which to view strategic priorities. Its documentation and widespread teaching in business schools and accelerator programs solidified it as a standard reference model for entrepreneurial progression.
What it is for
The Profitability stage decision exists to force a fundamental strategic choice about the source and use of a company's financial fuel. Its primary function is to determine whether the business will prioritize generating its own operating capital from customer revenue or will continue to rely on external capital from investors. This decision directly dictates the company's operational tempo, hiring strategy, and market expansion plans. It serves as a pressure test for the underlying business model, demanding proof that unit economics are sound and that revenue can sustainably exceed all costs. The stage is designed to move the founder from a mindset of growth-at-all-costs to one of sustainable economic value creation. Ultimately, it exists to establish financial self-determination and reduce existential risk, creating a stable platform for all future decisions.
Overview
The Profitability stage is the point in a founder's journey where the pursuit of positive net income becomes the central, governing objective of the company. It follows stages typically focused on product development and initial market validation, and precedes considerations of scaled growth or market dominance. At this juncture, the founder must shift the organization's focus from burning capital to extend runway to generating capital to ensure permanence. This involves rigorous cost management, price optimization, and often, difficult prioritization of revenue-generating activities over speculative projects. The operational cadence changes to a meticulous monitoring of cash flow, gross margins, and operating expenses. Successfully navigating this stage results in a company that controls its own destiny, while failure to achieve it can lead to a perpetual dependency on external funding or insolvency.
What to know
Achieving profitability requires a deliberate and often difficult operational retrenchment, not merely an expectation of linear growth. Founders must understand that the metrics that mattered in prior stages, like user growth or feature velocity, become secondary to financial metrics like contribution margin and burn rate. It is critical to know that profitability is not a one-time event but a sustainable state that must be engineered into the business processes and culture. This stage often exposes weaknesses in the business model that were previously masked by investor capital, such as poor customer retention or inefficient customer acquisition costs. Founders should be aware that the pursuit of profitability can conflict with short-term growth targets, potentially ceding market share to well-funded competitors. Importantly, the path to profitability is unique to each business and is highly influenced by industry dynamics, capital intensity, and competitive landscape.
Common questions
How long should a founder plan for the transition to profitability to take, and is there a standard timeline for this stage? What are the most common operational changes required to reach profitability, and which departments are typically impacted most significantly? Can a company pursue rapid growth and profitability simultaneously, or are these objectives fundamentally at odds during this stage? How does the definition of profitability differ for a software-as-a-service company versus a physical product manufacturer? What key financial metrics should a founder track daily or weekly during this push, beyond simple net income? Does achieving profitability mean the company should stop seeking any external investment, or does it simply change the terms and necessity of such funding?
Pros and cons
A primary advantage of prioritizing profitability is the attainment of strategic independence and resilience; the company is no longer subject to the whims of external capital markets or investor sentiment. It forces operational discipline and efficiency, often leading to a leaner, more focused organization with a clearer value proposition. Profitability provides a stable foundation for controlled, organic growth and allows the founder to make decisions based on long-term company health rather than short-term investor expectations. A significant drawback is that the intense focus on cost control and immediate revenue can stifle innovation and long-term research and development initiatives. The common mistake is pursuing profitability through drastic, across-the-board cuts that damage product quality or team morale, ultimately harming the core business. Founders often regret choosing this path too late, after burning through excessive capital and having no leverage with investors, or too early, before achieving sufficient product-market fit to generate meaningful revenue.
Who it suits
The Profitability stage decision suits founders whose primary motivation is building a self-sustaining, long-term independent business rather than pursuing rapid, capital-intensive market dominance. It is well-suited to businesses in industries with proven, stable monetization models and moderate growth ceilings, where winner-take-all dynamics are less pronounced. Founders with a risk-averse temperament or those who wish to maintain maximum equity and control will find this path aligns with their goals. It also suits businesses that can achieve strong unit economics early, where the cost to acquire and serve a customer is significantly lower than their lifetime value. This path is less suited for founders operating in hyper-competitive, winner-take-all markets where massive upfront investment in growth and network effects is a prerequisite for survival. It is also a challenging fit for deep-tech or infrastructure-heavy ventures that require years of unprofitable research and development before a revenue model can be established.
Latest Profitability news
Latest reporting
Cloover hits profitability with $350M
Cloover, a Berlin-based energy platform for home electrification, has become profitable three years after its 2023 launch, achieving a revenue run...
Bootstrapped and Profitable: Taimi and Hily Set Sights on IPO Readiness
Taimi and Hily, two mobile dating apps, are preparing for an initial public offering (IPO) after achieving profitability through bootstrapping...